
Business Insurance for Freelancers and Gig Workers: A Starter Guide
Ashley Walrath is a results-driven content strategist and copywriter known for creating clear, engaging content that connects brands with their audiences while supporting measurabl...
Andrea Perez is a bilingual content writer at Acceptance, where she creates strategic content for multiple brands within the insurance industry. With a background in journalism, ed...
Rose Carter is an accomplished content strategist and marketing leader with a proven track record of creating impactful, results-driven content. With expertise in writing, editing,...
Freelancing gives you flexibility, but it also means you’re responsible for protecting your business. Whether you make deliveries, design websites, provide consulting services, or work directly with customers, the right business insurance can help protect you from the financial impact of accidents, lawsuits, damaged equipment, and other unexpected problems.
The coverage you need depends on the work you do and the risks that come with it. Here’s what freelancers, independent contractors, and gig workers should know when choosing business insurance.
Key Takeaways
- Business insurance can help protect freelancers and gig workers from liability claims, property damage, professional mistakes, and other work-related risks.
- General liability and professional liability are two important coverages to consider, depending on the type of work you perform.
- Freelancers who drive for work should make sure their auto coverage accounts for business, delivery, or rideshare use.
- Homeowners and renters policies may provide limited or no coverage for certain business property and activities.
- Your coverage should reflect your services, equipment, work location, contracts, and whether you drive or have employees.
Understanding Insurance Needs for Freelancers and Gig Workers
Freelancers, independent contractors, and gig workers face different risks depending on how and where they work.
A graphic designer may face a claim that an error caused a client financial loss. A photographer may need to protect expensive equipment. A house cleaner could accidentally damage a customer’s property, while a delivery driver faces risks associated with using a vehicle for work.
Insurance provided by a client or gig platform may not cover every situation. Review any coverage offered through a platform carefully, including its limits, exclusions, and when coverage applies.
Your business insurance should reflect the work you actually perform. Understanding why small businesses need insurance can help you identify potential risks.
Core Business Insurance Types for Freelancers
The right combination of coverage depends on your services, work location, equipment, and potential liability risks.
Professional Liability Insurance (Errors & Omissions)
Professional liability insurance, also called errors and omissions (E&O) insurance, can help with certain claims alleging that a mistake in your professional services or advice caused a client financial loss.
This coverage may be particularly relevant for:
- Consultants
- Designers
- Marketing professionals
- Technology professionals
- Accountants
- Other freelancers who provide professional services or advice
For example, suppose a client claims that an error in your work caused them a financial loss. Depending on the circumstances and policy, professional liability insurance may help with covered legal expenses, settlements, or judgments.
General Liability Insurance
General liability insurance can help protect your freelance business against certain third-party claims involving bodily injury, property damage, and other covered liabilities.
For example, you might accidentally damage furniture while working at a client’s home, or a client could get hurt while visiting your workspace. General liability insurance may help with covered costs associated with those incidents.
This coverage can be especially important if you:
- Meet clients in person
- Work at customer locations
- Have clients visit your workspace
- Attend markets, events, or trade shows
- Handle other people’s property
Some clients, landlords, venues, or contracts may also require proof of insurance before you’re allowed to perform work.
Business Owners Policy (BOP) and In-Home Business Options
A business owners policy, commonly called a BOP, generally combines certain business property and liability coverages into one policy.
Business property coverage can help protect covered items you rely on for work, such as computers, cameras, tools, office furniture, or other equipment.
If you work from home, don’t assume your homeowners or renters policy provides all the business protection you need. Coverage for business property or business-related liability may be limited or excluded.
Depending on your business, an endorsement, in-home business policy, or separate commercial coverage may be appropriate. Learn more about what kind of insurance a home-based business may need.
You can also learn more about what commercial insurance is and how different types of business coverage work.
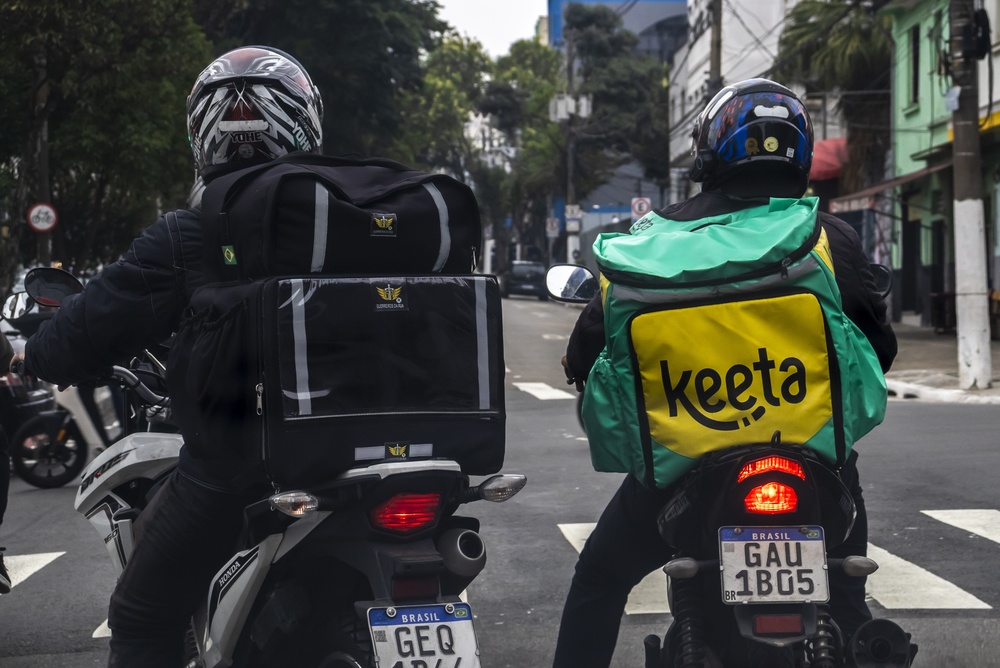
Insurance for Gig Drivers and Mobile Freelance Work
Personal auto insurance is primarily designed for personal vehicle use. Delivery, rideshare, or other business use may be treated differently depending on your insurer and policy.
Platform-provided insurance can also have specific requirements and limitations. Don’t assume you’re fully covered simply because an app provides some insurance while you’re working.
Using Your Personal Vehicle for Business
Tell your insurer how you actually use your vehicle.
Regular deliveries, rideshare driving, transporting work equipment, or traveling between client locations may affect the type of auto coverage you need. Depending on your work and insurer, you might need an endorsement or a separate commercial auto policy.
Freelancers who regularly drive for business should ask about commercial auto insurance and review how their existing policy handles business use.
Gig Insurance Solutions and Platform Coverage Gaps
Some gig platforms provide insurance protection for drivers or workers, but when and how that coverage applies varies.
For example, coverage may depend on whether you’re logged into an app, waiting for a job, actively completing a job, or transporting a customer or delivery.
Before relying on platform coverage:
- Read the platform’s insurance terms.
- Check when coverage begins and ends.
- Review coverage limits and deductibles.
- Find out whether your personal policy allows the type of work you’re doing.
- Tell your insurer about your gig or business use.
Understanding how your personal, business, and platform coverage work together can help you identify potential gaps before a claim.
Protecting Your Workspace, Data, and Income
Your business may depend on equipment, technology, data, and your ability to work. Consider what would happen if your laptop were stolen, equipment was damaged, or important client information became inaccessible.
Home Offices, Equipment, and In-Home Business Policies
If you work from home, keep a record of the business property you rely on. Note:
- What you own
- Its approximate replacement cost
- Where it’s stored
- Whether you take it to client locations
- How important it is to your ability to work
Depending on your situation, you may need additional business property coverage, an endorsement, an in-home business policy, or a BOP.
Cybersecurity and Data Protection for Freelancers
If you store sensitive client information, accept electronic payments, or depend on online systems, cyber insurance may be worth considering.
Depending on the policy, cyber coverage may help with certain expenses resulting from covered data breaches, cyberattacks, or other technology-related incidents.
Insurance shouldn’t replace good cybersecurity practices. Strong passwords, multi-factor authentication, secure data storage, software updates, and regular backups can help reduce risk.
Other Insurance Considerations for Self-Employed Workers
Health, disability, and life insurance aren’t business liability or property coverage, but self-employed workers may want to review them separately.
If an illness or injury prevents you from working, disability insurance may provide income protection for qualifying disabilities, subject to the policy terms.
Life insurance can provide financial protection for people who depend on your income, particularly if you have personal or business financial obligations. Learn more about life insurance for small business owners.
If your freelance business grows and you hire employees, you may also have additional insurance requirements. These vary by state and business type.
How to Choose and Buy Business Insurance as a Freelancer
Choose coverage based on the work you actually do and the risks your business faces.
- List your risks. Consider your services, equipment, work locations, customers, data, and vehicle use.
- Review your contracts. Clients, landlords, or platforms may have specific insurance requirements.
- Check your existing coverage. Find out what your personal home and auto policies do and don’t cover when you’re working.
- Identify your biggest financial exposures. Consider which accident, lawsuit, mistake, or property loss could hurt your business most.
- Compare coverage options. Look at policy limits, deductibles, exclusions, and coverage details rather than choosing based on premium alone
- Review your coverage as your business changes. New clients, services, equipment, employees, or work locations can create new risks.
Assessing Your Risks and Coverage Gaps
Match your major business risks with the coverage designed to address them:
- A professional mistake allegedly causes a client financial loss: Professional liability insurance may help with a covered claim.
- A customer is injured at your workspace: General liability insurance may help with a covered claim.
- You accidentally damage a client’s property: General liability insurance may apply, depending on the circumstances and policy.
- Business equipment is stolen or damaged: Business property coverage may help with a covered loss.
- You’re involved in an accident while driving for work: The appropriate auto coverage may be an endorsement to your existing policy or a commercial auto policy, depending on the work you do, your insurer, and the policy.
- Sensitive client data is compromised: Cyber insurance may help with certain covered events.
- An employee is injured while working: Workers’ compensation may apply, depending on state requirements and your business.
Written contracts, safe work procedures, secure data practices, and accurate records can also help reduce business risks.
Working With an Agent and Comparing Options
Before speaking with an insurance agent, gather basic information about your business:
- The services you provide
- Where you work
- Your business equipment
- Whether clients visit your workspace
- Whether you drive for work
- Whether you have employees
- Any insurance requirements in your contracts
- Your current personal and business coverage
Be clear about how you operate. Delivery work, client visits, expensive equipment, or other business activities can affect the coverage you need.
Protect Your Freelance Business with the Right Coverage
The right insurance depends on what you do, where you work, what equipment you rely on, and the risks you face. Review your current home and auto policies, then compare business coverage for risks they may not address.
Acceptance Insurance can help you explore business insurance options for your freelance or independent business. Get a quote online, visit a local Acceptance Insurance office, or call us at 877-405-7102 to discuss your coverage needs.
Frequently Asked Questions
Do I Really Need Business Insurance If I’m a Part-Time Freelancer?
Possibly. Working part-time doesn’t eliminate business risks. A freelancer can still accidentally damage someone’s property, face a professional liability claim, lose expensive business equipment, or experience another covered loss.
Will My Clients or Platform Companies Cover Me If Something Goes Wrong?
Don’t assume they will. A client or gig platform may have its own insurance, but that doesn’t necessarily mean you’re fully protected.
Review your contract or platform terms to understand what coverage is provided, when it applies, and what you’re expected to insure yourself.
How Much Liability Insurance Should a Freelancer Carry?
There’s no single liability limit that’s right for every freelancer. The appropriate amount depends on your work, contracts, potential losses, business assets, and budget.
Some clients or venues may require specific limits. Review those requirements and discuss your potential exposure with an insurance professional when selecting coverage.
What Happens If I Use My Personal Car for Both Personal and Gig Work?
Tell your insurer how you’re using your vehicle. Personal auto policies may handle business, delivery, or rideshare use differently, and some activities may require additional coverage.
What Business Insurance Does a Freelancer Need?
It depends on the type of work you do. A consultant may prioritize professional liability coverage, while a photographer may need general liability and protection for expensive equipment. A delivery or rideshare driver should pay particular attention to auto coverage.
Does Homeowners Insurance Cover Freelance Business Equipment?
It may provide limited coverage in some situations, but you shouldn’t assume your business equipment is fully protected under a homeowners policy.
Review your policy limits and exclusions and consider separate business property coverage if you depend on expensive computers, cameras, tools, inventory, or other equipment.
How Often Should I Review or Update My Freelance Business Insurance?
Review your coverage periodically and whenever your business changes significantly. For example, contact your agent when you add a new service, buy expensive equipment, begin driving for work, move your workspace, hire employees, or take on contracts with new insurance requirements.

Ready to Get a Quick Quote?

